Property appraisals in Phoenix
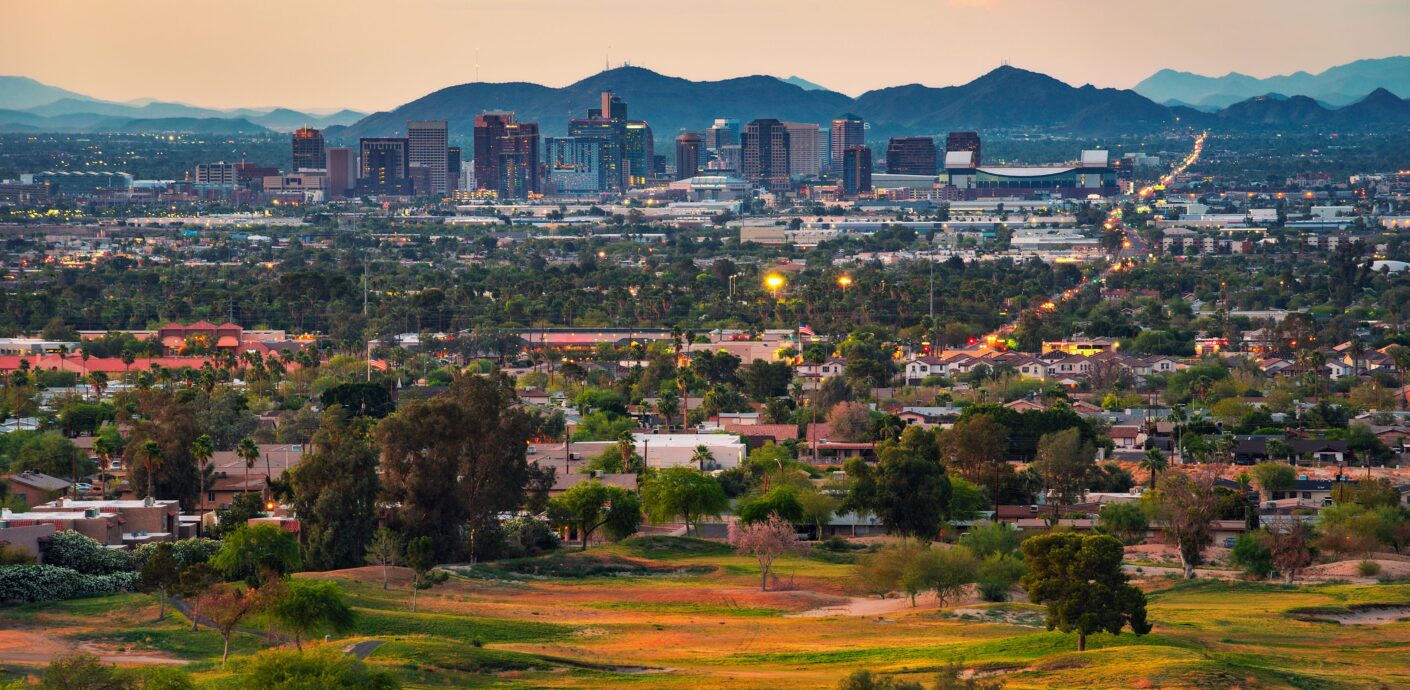
PahRoo serves the Phoenix metro as a service area. The firm is based in the Chicago area, and Phoenix assignments get the same standards, applied to a market with a very different personality: master-planned subdivisions, production builders, rapid growth, and a housing stock where thousands of homes share a handful of floor plans.
That sameness is exactly why appraisal here is harder than it looks.
Valuing homes in a market of look-alikes
A subdivision of near-identical homes seems like the easiest possible appraisal environment. Review appraisers know it is where some of the worst work hides. When a subdivision holds hundreds of homes, recent sales inside it almost always exist, and a report that reaches across a highway or into a superior product line for its comparables while ignoring in-subdivision sales is a classic red flag. So are per-square-foot adjustments out of line with what the local market actually pays.
Uniform housing stock is also the segment most exposed to purely algorithmic valuation, and that is precisely the argument for professional judgment here: when every model estimate looks plausible, the errors are invisible until someone checks the comps, the conditions, and the adjustments against the actual market. Within a tract, value differences concentrate in the things models miss: condition, upgrades versus builder-grade finishes, lot position and orientation, and premiums that vary by phase.
A boom-and-bust market with a long memory
Phoenix has been at the leading edge of national housing cycles more than once. In the 2008 crisis, Arizona was among the first and hardest-hit foreclosure markets, part of a wave that moved from California, Arizona, and Nevada eastward over roughly two years. Fast-growth markets carry a specific valuation risk in the other direction too: during a boom, the gap between a new-construction contract signing and the appraisal’s effective date can stretch to a year and a half, and in a fast-appreciating market that timing gap becomes a real valuation problem.
The lesson for anyone relying on a Phoenix valuation: in a market that moves fast, the effective date and the data’s freshness are not technicalities. They are the number.
Arizona practice notes
Arizona is a disclosure-friendly state; affidavits of value are filed with deed records, which gives appraisers here a public data foundation that some neighboring markets lack. Good data does not replace judgment, but it does mean a Phoenix appraisal can be built on verifiable public transaction records, and it should be.
What we appraise in the Phoenix metro
- Single-family homes, from production subdivisions to custom and luxury properties
- New construction, including contract-versus-completion valuation questions
- Condominiums and townhomes
- Commercial and income-producing property
- Assignments for lending, estate and date-of-death, divorce, tax appeal, and general market value
Intended use in a fast market
The reason for the appraisal decides its scope and effective date everywhere, but Phoenix’s velocity gives the effective date extra weight. A lending assignment values the property for an underwriting decision being made now. An estate assignment is retrospective, valuing as of a date of death, which in a market that can move double digits in a year means the historical data has to be handled precisely. Divorce and tax appeal assignments each face their own audience and their own scrutiny. Say what the appraisal is for at engagement, and the analysis gets built for that decision, on that date.
The desert specifics that belong in the analysis
Beyond the tract-home problem, Phoenix valuation carries local variables an outside estimate never prices: lot orientation and shade in a climate where afternoon sun exposure is a livability factor, pools as near-standard amenities whose contributory value still varies by segment, HOA and master-plan amenity structures that differ community to community, and the premium gradients between established neighborhoods and new phases still being built out. None of these are exotic. All of them are exactly the kind of condition-and-context detail that automated models structurally cannot see, which is why they assume every property is average.
Engaging PahRoo in Phoenix
Bring the intended use and, for new construction, the contract and the timeline, because in this market timing is part of the analysis. Contact PahRoo to discuss the assignment.